Finance NTAP AI infrastructure Oct 11, 2026
The answer, and the question behind it
Insider Monkey’s October 10 report, syndicated by Yahoo Finance, recapped the October 1 Mad Money lightning round. A caller said they had owned NetApp for years with little movement before the shares surged from an April low around $96 to $216. Jim Cramer’s answer was to hold: he called NetApp a “great situation” and said he would not worry.
That is a television host’s opinion, not a valuation model. The decision-useful question is whether the business changed enough to support the repricing. NetApp’s latest reported quarter says yes on growth and earnings power; it is less specific on how much demand is truly AI-driven.
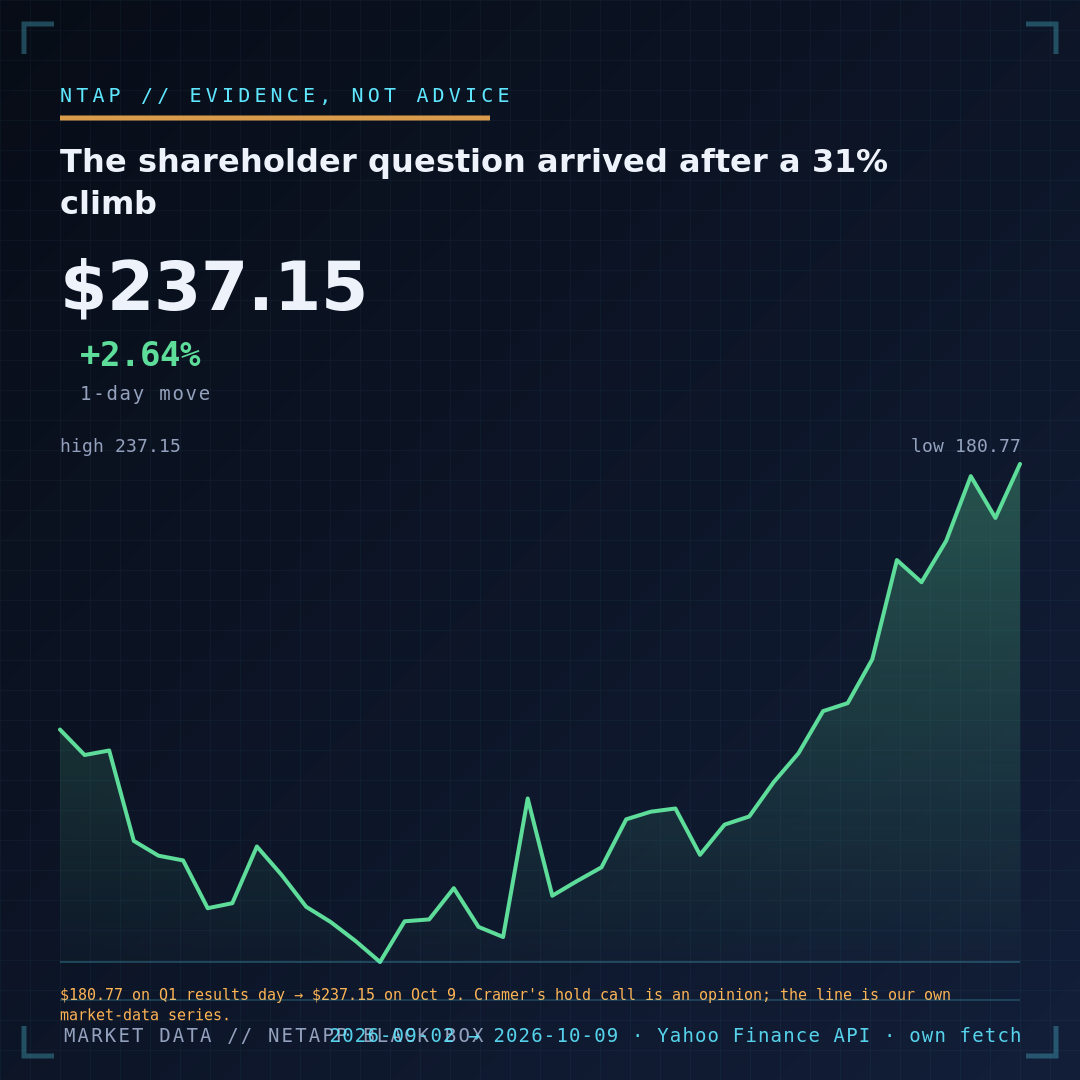
scripts/bbx_brand.py from state/ntap_market.json; no third-party chart screenshot.The operating case in six numbers
| Q1 FY27 measure | Result | Why it matters |
|---|---|---|
| Net revenue | $2.025B, +30% | Growth was broad enough to lift both segments. |
| Hybrid Cloud | $1.819B, +30% | About 90% of quarterly revenue; the installed-platform business still dominates. |
| Public Cloud | $206M, +28% | Fast growth, but only about 10% of the reported mix. |
| All-flash revenue | $1.309B, +47% | The clearest disclosed proxy for high-performance storage demand. |
| Non-GAAP operating margin | 31.9%, +610 bps | Revenue growth converted into operating leverage. |
| Non-GAAP EPS | $2.58, +66% | Earnings grew more than twice as fast as revenue. |
The margin label matters. NetApp reported a 23.9% GAAP operating margin and 31.9% non-GAAP; mixing the two would overstate comparability. The cash line is also a counterweight: free cash flow was $401M, down 35% year over year, even as earnings accelerated.
The guide moved up materially
After Q1, NetApp raised full-year FY27 revenue guidance to $7.975B–$8.225B. The midpoint, $8.10B, is $725M above the midpoint of May’s initial $7.325B–$7.575B range. Full-year non-GAAP operating-margin guidance moved to 30.3%–31.3%, and non-GAAP EPS to $9.73–$10.03.
For Q2, management guided revenue to $2.025B–$2.175B, non-GAAP gross margin to 67.0%–68.0%, non-GAAP operating margin to 30.9%–31.9%, and non-GAAP EPS to $2.54–$2.64. This is the strongest quantitative support for the bullish response: the company did not merely beat a quarter; it reset the year.
What the numbers do—and do not—say about AI demand
NetApp attributed momentum to AI and hybrid multicloud initiatives and highlighted its DataPelago acquisition. The mix is consistent with infrastructure demand: all-flash grew 47%, product revenue grew from $654M to $987M, and both Hybrid Cloud and Public Cloud expanded near 30%.
But NetApp does not disclose AI revenue, AI bookings, an AI backlog or AI-specific margin. All-flash includes many non-AI workloads, while AI projects can also consume public-cloud and hybrid-flash services. The defensible conclusion is that demand for the storage building blocks used by AI rose sharply; the filing does not let us quantify how much of the growth came from AI itself. Our AI hub tracks the product evidence separately from the market narrative.
The read-through for storage customers
- Budget for flash demand, not a stock chart. A 47% all-flash revenue increase suggests tight attention to platform availability, support capacity and implementation lead times, but it does not prove a shortage for any particular system.
- Ask vendors to decompose “AI-ready.” Require workload-level throughput, latency, metadata scaling, protection and restore evidence. Our performance-monitoring guide shows the operational measurements that survive the marketing label.
- Keep cloud economics in proportion. Public Cloud grew quickly but represented roughly one-tenth of reported revenue. Compare control, egress, operations and data-gravity costs with the on-premises path through the cloud and hybrid hub.
- Watch support as the installed base expands. Support revenue rose to $720M from $647M. Buyers should test upgrade windows, escalation coverage and lifecycle commitments alongside acquisition price.
Bottom line
Cramer gave the shareholder a clear answer; NetApp gave the market a measurable reason to consider it. Revenue grew 30%, all-flash grew 47%, non-GAAP operating margin expanded 610 basis points, and the full-year guide rose sharply. The caveat is equally clear: none of those lines isolates AI demand, and weaker free cash flow prevents the quarter from being a one-number victory. For customers, the read-through is stronger flash and hybrid-platform demand—not permission to accept an unquantified AI premium.