Analysis of the triggering ad-hoc-news listing, corroborated by The Fly report carried by TipRanks and checked against NetApp's Q1 FY27 results.
NTAP TD COWEN FINANCE AI INFRASTRUCTURE 2026-10-21
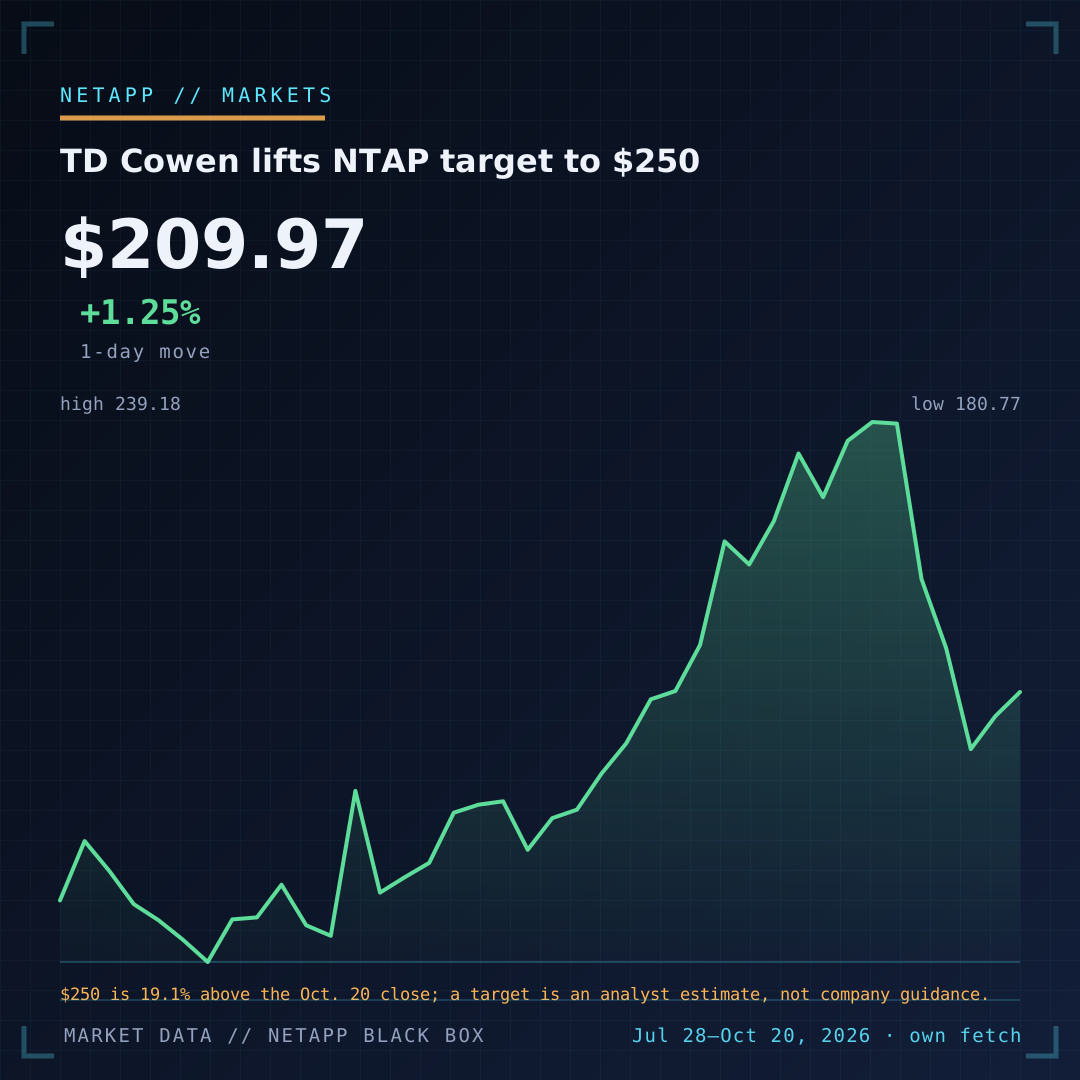
The call and the tape
TD Cowen lifted its target to $250 from $200 on October 6 and maintained a Buy rating. NTAP closed that session at $228.45, putting the target 9.4% above the close. By October 20 the stock was $209.97; the same target then implied 19.1% upside.
That changing gap is why a target must not be mistaken for a measured return. Our series shows NTAP up 1.25% on October 20, down 12.15% over five sessions, up 5.97% over one month and up 26.08% over three months. Those horizons describe a volatile repricing, not proof that the analyst's assumptions are right.
The operating scorecard
NetApp's latest quarter supplied real support for a higher-growth thesis: Q1 FY27 revenue reached $2.025 billion, up 30% year over year; billings were $2.057 billion, up 36%. Hybrid Cloud contributed $1.819 billion, up 30%, while Public Cloud reached a record $206 million, up 28%.
GAAP gross profit of $1.419 billion implies a 70.1% GAAP gross margin. GAAP operating margin was 23.9% and non-GAAP operating margin was 31.9%. The counterweight was cash conversion: operating cash flow fell 25% to $503 million and free cash flow fell 35% to $401 million. A bullish valuation has to absorb both the growth and the cash-flow decline.
Guidance defines the next test
Management guided Q2 FY27 revenue to $2.025–$2.175 billion, GAAP gross margin to 66.0–67.0% and GAAP operating margin to 24.9–25.9%. It raised full-year revenue guidance to $7.975–$8.225 billion and non-GAAP EPS guidance to $9.73–$10.03.
The midpoint is $2.10 billion for Q2 and $8.10 billion for the year. Those are company guideposts that can be tested; $250 is an analyst valuation judgment layered on top of them.
AI demand: strong evidence, incomplete mix
All-flash array revenue reached a record $1.3 billion, up 47%, materially faster than total revenue. NetApp also acquired DataPelago and tied its momentum to AI and hybrid multi-cloud work. That supports demand for high-performance data infrastructure.
It does not establish an AI revenue figure. NetApp reports Hybrid Cloud and Public Cloud segments, not AI and non-AI revenue; all-flash also serves databases, virtualization and general enterprise workloads. The full analyst note is unavailable, so we cannot responsibly say which AI assumptions TD Cowen placed in its model.
The storage read-through: more compute creates a data-path test
The earnings evidence says customers are buying more flash and cloud capacity; it does not mean every AI proposal is justified. Storage teams still need to validate throughput, metadata behavior, checkpoint windows, recovery objectives and usable capacity against their own pipeline.
A rising target can strengthen a vendor's market narrative, but it does not change support matrices, performance limits or contract terms. Procurement should demand deployment evidence and lifecycle cost rather than treating equity research as a sizing input.
Use the site's capacity-planning guide to separate usable capacity, growth headroom and protection overhead. Then validate throughput, concurrency, small-file behavior, checkpoint windows and recovery objectives against the actual pipeline. The AI topic hub and financials hub keep product evidence separate from market claims.
What to watch next
- Revenue: whether Q2 lands inside $2.025–$2.175 billion.
- Margin: whether growth holds while GAAP gross margin moves into the guided 66–67% range.
- Cash: whether free cash flow recovers from the 35% year-over-year decline.
- AI proof: quantified bookings, backlog or deployment evidence rather than an inferred AI share of all-flash revenue.
Bottom line
The $250 target is 25% above TD Cowen's prior target and was 19.1% above NTAP's October 20 close. The operating case behind a richer valuation includes 30% revenue growth, 47% all-flash growth and raised guidance; the caution case includes weaker cash flow and no disclosed AI revenue mix. Customers should use the financial momentum as context, then qualify storage on workload evidence.
Sources: NetApp Q1 FY27 results · NetApp Q1 FY27 Form 10-Q · TD Cowen action reported by The Fly/TipRanks · ad-hoc-news listing via Google News. Market prices: state/ntap_market.json. Calculations are NetApp Black Box analysis. Not investment advice.