NTAP FINANCE AI INFRASTRUCTURE 2026-10-22
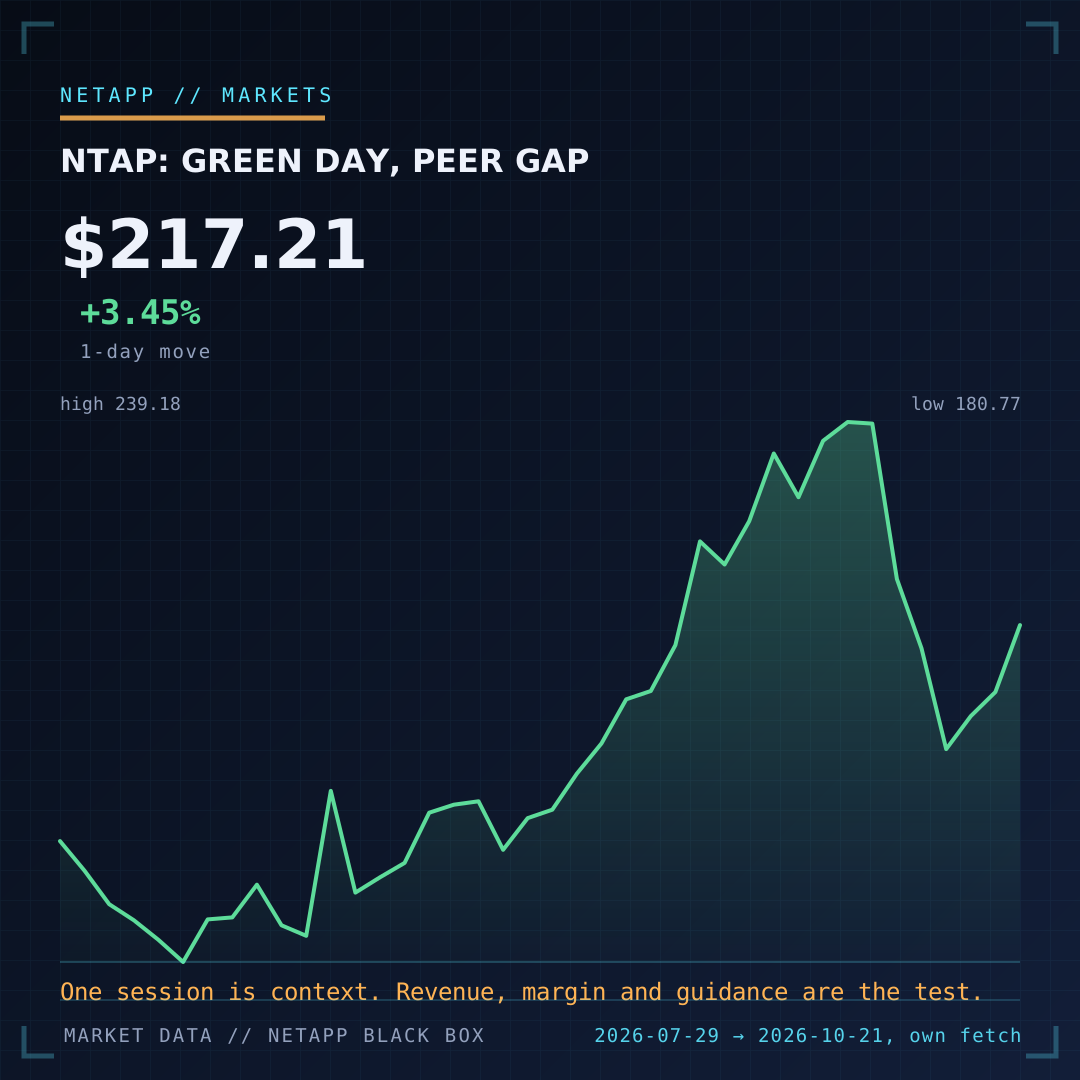
state/ntap_market.json; no third-party chart image is reproduced.The move: positive day, relative underperformance
NTAP closed October 21 at $217.21, up 3.45% from $209.97. MarketWatch described the shares as underperforming because two named comparison stocks gained more during the same session—not because NTAP fell. A one-day peer ranking also is not a clean storage-industry benchmark: the comparison set spans networking, cloud and storage businesses with different revenue drivers.
Our independently fetched series puts the move in a wider frame: NTAP was down 2.25% over five sessions, up 12.60% over one month, up 31.93% over three months and up 95.65% year to date. Those returns explain why a green session can still look modest relative to peers, but the automated report does not establish what caused the move.
The numbers behind the business
NetApp's latest filed quarter is Q1 FY27. Revenue was $2.025 billion, up 30% year over year; billings were $2.057 billion, up 36%. Hybrid Cloud revenue rose 30% to $1.819 billion, while Public Cloud revenue rose 28% to a record $206 million.
GAAP gross profit of $1.419 billion on $2.025 billion of revenue implies a 70.1% GAAP gross margin. GAAP operating margin was 23.9% and non-GAAP operating margin was 31.9%. The counterweight is cash conversion: operating cash flow fell 25% to $503 million and free cash flow fell 35% to $401 million. Any reading of the rally should hold growth and weaker cash flow together.
Guidance makes the next test explicit
Management guided Q2 FY27 revenue to $2.025–$2.175 billion, with GAAP gross margin of 66.0–67.0% and GAAP operating margin of 24.9–25.9%. Full-year guidance was raised to $7.975–$8.225 billion of revenue and $9.73–$10.03 of non-GAAP EPS.
The midpoint is $2.10 billion for Q2 and $8.10 billion for the year. Those are measurable company commitments; a daily share-price comparison is not.
What the quarter does—and does not—say about AI
All-flash array revenue reached a record $1.309 billion, up 47%, substantially faster than company revenue. NetApp also acquired DataPelago and positioned its platform for AI and hybrid-cloud data work. That is meaningful evidence of demand for high-performance data infrastructure.
It is not a disclosed AI revenue number. NetApp reports Hybrid Cloud and Public Cloud segments, not AI and non-AI revenue, and all-flash systems serve databases, virtualization and other enterprise workloads. The defensible conclusion is that flash demand accelerated; the AI share of that demand remains not reported.
Read-through for storage customers
The operating momentum can support product investment and lifecycle confidence, but a stock move changes no ONTAP support matrix, sizing limit or contract term. Storage buyers should translate the demand signal into workload questions: sustained throughput, metadata intensity, checkpoint windows, recovery objectives and usable capacity after protection overhead.
Use the capacity-planning guide to model usable capacity and headroom, then use the AI topic hub to separate architecture evidence from market narrative. The financials hub tracks the company metrics behind the platform.
Bottom line
NTAP gained 3.45% on October 21 while trailing two of MarketWatch's named peers. The more durable signal is NetApp's 30% revenue growth, 47% all-flash growth and raised guidance; the caveats are weaker cash flow and no disclosed AI revenue mix. For customers, that argues for confidence in demand—not for skipping workload validation.
Sources: MarketWatch item via Google News · NetApp Q1 FY27 results · NetApp Q1 FY27 Form 10-Q. Returns and margin calculations are NetApp Black Box analysis from the cited inputs and state/ntap_market.json. Not investment advice.